Residential signal.
ICE reported average homeowner coverage costs of $209 per month in Q2 2026, up 8.7% year over year. In ICE’s study, homeowners who switched insurers saw an average 6.6% reduction, while those who stayed saw a 10.4% increase. These are residential outcomes—not projected commercial savings. [1]
Commercial reality.
Federal Reserve research found multifamily insurance expense rose from $39 to $68 per unit per month (inflation-adjusted) between 2019 and 2024. Meanwhile, Marsh reported U.S. commercial property renewal rates fell an average of 10% in Q3 2026. Property-specific premiums may still rise. [2, 3]
Six moves to protect investment cash flow
1. Shop before renewal. Start 45–60 days early. Ask an independent commercial broker to price comparable options using the same coverage limits, property details, and loss history.
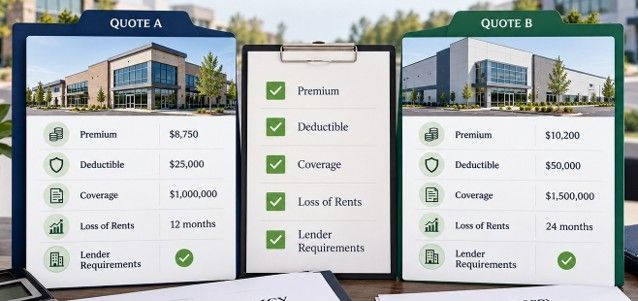
2. Compare protection—not only price. Check replacement cost, roof valuation, coinsurance, business-income or loss-of-rents coverage, and flood, wind/hail or named-storm exclusions.
3. Calculate the real deductible. A 5% storm deductible on a $2 million insured building could mean $100,000 out of pocket, compared with $40,000 at 2%. Confirm how the percentage is calculated.
4. Improve insurability. Document roof maintenance, wind mitigation, updated systems, and safety controls. Ask insurers which improvements qualify for more favorable terms.
5. Stress-test the lender’s numbers. If NOI is $104,000 and annual debt service is $80,000, DSCR equals 1.30×. A $12,000 insurance increase without offsetting income lowers DSCR to 1.15×.
6. Coordinate before closing. Confirm the insurer, limits, deductible caps, and lender requirements; review lease pass-throughs, fund reserves, and verify flood and wind policies where applicable.
Quote comparison: the lowest premium may not be the best deal